By Alicia Moreno · Research Writer
Published · Updated
Answer in brief
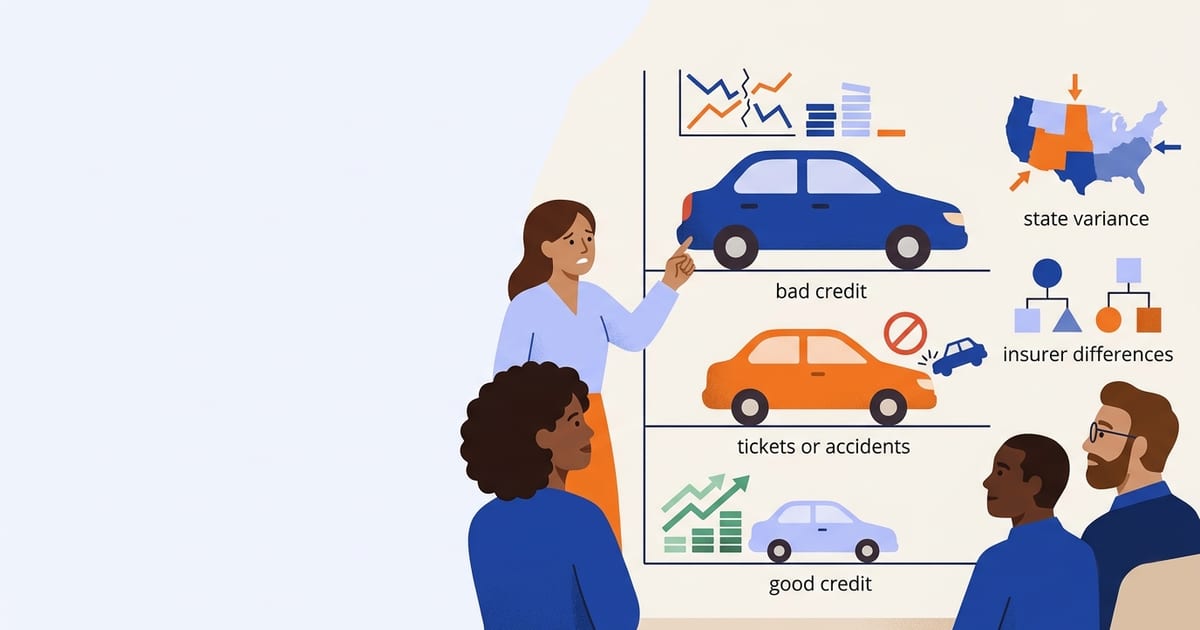
In states that permit credit rating, drivers with poor credit commonly pay 60–110% more than drivers with excellent credit for identical coverage—in many states a larger penalty than a single at-fault accident. The gap varies enormously by insurer: some apply a modest 10–20% spread, others more than double the premium. That variance is the opportunity. A poor-credit driver who compares five insurers will typically find a spread of 40% or more between the highest and lowest quote.
Typical premium by credit tier
| Credit tier | Typical relative premium | Range across insurers |
|---|---|---|
| Excellent (780+) | 100% | — |
| Good (700–779) | 110–125% | 105–135% |
| Fair (620–699) | 135–160% | 115–185% |
| Poor (below 620) | 160–210% | 120–260% |
Compared with driving record
A single at-fault accident typically adds 30–60%. A speeding ticket adds 10–25%. Poor credit, at a heavily weighted insurer, can add 100%. In other words, for many drivers credit is the single largest factor they are not thinking about—and unlike a ticket, it does not expire on a schedule.
Why the range across insurers is so wide
Each insurer builds its own scoring model and decides how many tiers to use and how far apart they are. Some use credit to sort into three tiers with modest differences; others into twenty or more with steep ones. The same driver falls into very different places in different companies' models, and that is why comparing produces larger savings for poor-credit drivers than for almost anyone else.
Questions & answers
How much does bad credit raise car insurance?
Commonly 60–110% versus excellent credit, in states that allow credit rating; the range across insurers is very wide.
Is bad credit worse than an accident for insurance?
At many insurers, yes—poor credit can add more than a single at-fault accident.
Does the credit penalty ever expire?
Not on a schedule. It falls as your score improves and the insurer re-pulls it, typically at renewal.
Terms used in this guide
- Credit-based insurance score
- A score derived from your credit report and weighted to predict insurance losses. Used as a rating factor in most states; banned in California, Hawaii and Massachusetts, with Michigan barring use of the credit score itself.
- Rating tier
- A pricing group with its own rates. Credit is a primary tier factor at many insurers; the number and spread of tiers vary widely.
- Premium
- The price of a policy, per six or twelve months.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Credit-based insurance scores (insurance topic) — National Association of Insurance CommissionersState insurance regulatorIn most states insurers may not use a credit score as the sole reason to raise rates or decline, cancel or non-renew; many states require adverse-action notices.
- State chart: use of credit reports/scoring in underwriting — National Association of Insurance Commissioners (2025)State insurance regulatorState-by-state statutory summary; e.g. Massachusetts (auto rates may not be based on credit), Michigan (credit score prohibited, MCL 500.2162), Maryland (credit may rate a new auto policy only).
- Background on: Insurance scoring — Insurance Information InstituteIndependent researchWhat credit-based insurance scores are; Arkansas regulator data showing credit lowered premium on ~57% of auto policies and raised it on ~23%.
- Trends and Insights: Auto insurance rates (June 2024) — Insurance Information Institute (2024)Independent researchWhy premiums rose 2021–2024: crash frequency and severity, repair and labour inflation, vehicle technology, attorney involvement.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Auto insurance — Insurance Information Institute (2025)Statistical dataNAIC countrywide average auto expenditure: $1,127 (2022), $1,282 (2023); most expensive states in 2023 were Florida, Louisiana and New York.
- Insurance research and advocacy — Consumer Federation of AmericaConsumer guidanceConsumer-side research on auto insurance pricing, non-driving rating factors and affordability.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
How Credit Affects Auto Insurance Rates
What a credit-based insurance score is, how it differs from a credit score, how much it moves premiums, and why insurers are allowed to use it.
Guide
How to Improve Your Insurance Score
The specific actions that raise a credit-based insurance score—utilisation, on-time payments, disputing errors—and how to get your insurer to re-rate.
Guide
How to Compare Auto Insurance With Poor or No Credit
A comparison method tuned for credit-sensitive drivers: identical coverage, five quotes including non-standard and usage-based, direct credit questions, and timing around score changes.