By Alicia Moreno · Research Writer
Published · Updated
Answer in brief
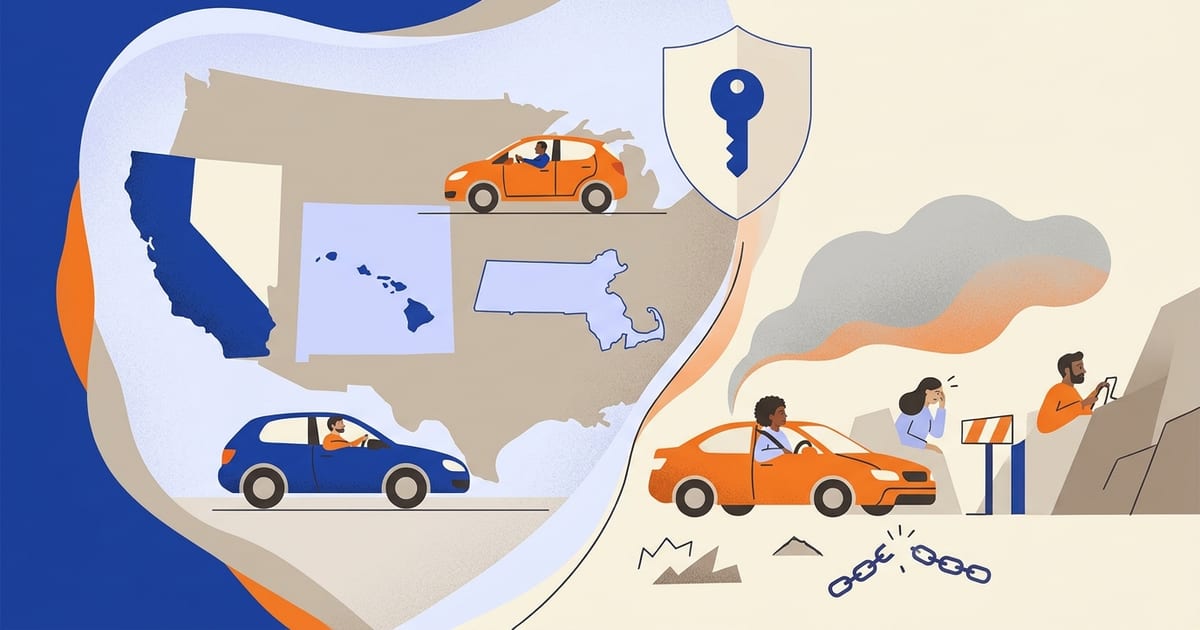
Three states prohibit credit-based insurance scoring for auto insurance outright: California (under its 1988 rating law, which also fixes the factors insurers must weight most), Hawaii and Massachusetts bar credit information from auto rating entirely. Michigan has prohibited the use of a driver's credit score since its 2019 reform took effect in 2020; the statute does not explicitly name credit-based insurance scores, and the state regulator requires insurers to show that any insurance score they file complies with the ban. Maryland bans its use for setting rates on new policies and renewals in most circumstances; Oregon and Utah bar its use to cancel or non-renew; several other states limit how heavily it may weigh or require exceptions for life events such as medical debt, divorce or job loss. Everywhere else it is permitted with disclosure rules.
Full prohibitions
| State | Rule |
|---|---|
| California | Credit may not be used in auto rating; rates must be based primarily on driving record, miles driven and years of experience |
| Hawaii | Credit prohibited as a rating factor |
| Massachusetts | Credit prohibited in auto rating and underwriting |
| Michigan | Credit score prohibited since July 2020 (MCL 500.2162); insurance-score filings must show compliance |
Significant restrictions
- Maryland — insurers may not use credit to rate, cancel or refuse new auto policies; limited use in renewals.
- Oregon — may be used for new business only, not for renewals, cancellation or non-renewal.
- Utah — may not be the sole basis for denial or non-renewal; limited at renewal.
- Nevada, Washington, Colorado and others — various caps, exception requirements and disclosure rules; Washington's attempted ban was overturned, but exception rules remain.
- Most states — require insurers to re-rate on request if your credit improves, and to make exceptions for extraordinary life circumstances.
What a ban means for drivers
In a ban state, your credit is irrelevant to your premium—rates depend on record, experience, mileage, territory, vehicle and coverage. Drivers with poor credit pay the same as drivers with excellent credit for the same risk. Drivers with excellent credit lose a discount they would get elsewhere.
Entries in this guide
Specific questions answered in more depth.
Entry
Moving to a State That Bans Credit in Auto Insurance: How Your Rate Changes
Discover what happens to your car insurance premium when moving to a state like California, Michigan, or Massachusetts where credit scoring is prohibited by law.
Entry
Michigan Auto Insurance Without Credit Checks: State Rules Explained
Understand Michigan's statutory ban on credit scoring under MCL 500.2111, how auto insurance rates are calculated, and how drivers can save on coverage.
Questions & answers
Which states don't allow credit scores for car insurance?
California, Hawaii and Massachusetts prohibit it outright; Michigan prohibits using your credit score; Maryland, Oregon and Utah restrict it heavily.
If I move to California, will my rate drop?
Credit will stop mattering, but California's base rates are set by other factors and are above the national average in many territories.
Can insurers use credit to cancel my policy?
In most states, no—credit may generally be used for pricing but not as the sole reason to cancel or non-renew.
Terms used in this guide
- Credit-based insurance score
- A score derived from your credit report and weighted to predict insurance losses. Used as a rating factor in most states; banned in California, Hawaii and Massachusetts, with Michigan barring use of the credit score itself.
- Extraordinary life circumstance exception
- A required exception to credit-based rating in many states when credit damage resulted from events such as serious illness, job loss, divorce, death of a family member, identity theft or disaster.
- Rating factor
- Any characteristic used to set a premium: record, age, territory, vehicle, mileage, coverage and—where allowed—credit.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- MCL 500.2111 — permitted and prohibited rating factors — Michigan Legislature, MCL 500.2111(4)Primary lawInsurers may not set auto rates on sex, marital status, home ownership, educational level, occupation, postal zone or credit score (as defined in § 2162).
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Vehicle Code § 16056 — minimum liability limits — California Legislative Information, Cal. Veh. Code § 16056Primary lawPolicies issued or renewed on/after 1 Jan 2025: $30,000 per person / $60,000 per accident bodily injury / $15,000 property damage. From 1 Jan 2035 the limits rise by $20,000 / $40,000 / $10,000 (to 50/100/25).
- Credit-based insurance scores (insurance topic) — National Association of Insurance CommissionersState insurance regulatorIn most states insurers may not use a credit score as the sole reason to raise rates or decline, cancel or non-renew; many states require adverse-action notices.
- State chart: use of credit reports/scoring in underwriting — National Association of Insurance Commissioners (2025)State insurance regulatorState-by-state statutory summary; e.g. Massachusetts (auto rates may not be based on credit), Michigan (credit score prohibited, MCL 500.2162), Maryland (credit may rate a new auto policy only).
- Background on: Insurance scoring — Insurance Information InstituteIndependent researchWhat credit-based insurance scores are; Arkansas regulator data showing credit lowered premium on ~57% of auto policies and raised it on ~23%.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- Insurance research and advocacy — Consumer Federation of AmericaConsumer guidanceConsumer-side research on auto insurance pricing, non-driving rating factors and affordability.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
How Credit Affects Auto Insurance Rates
What a credit-based insurance score is, how it differs from a credit score, how much it moves premiums, and why insurers are allowed to use it.
Guide
How to Find Auto Insurers That Don't Check Credit
Where to find auto insurers that do not use credit or weight it lightly—non-standard specialists, telematics-first programmes, pay-per-mile insurers—and how to ask.
Guide
Alternatives When Credit Is Raising Your Premium
Options for drivers whose credit is inflating their premium: life-circumstance exceptions, telematics and pay-per-mile, non-standard insurers, coverage changes and timing.