By Alicia Moreno · Research Writer
Published
Answer in brief
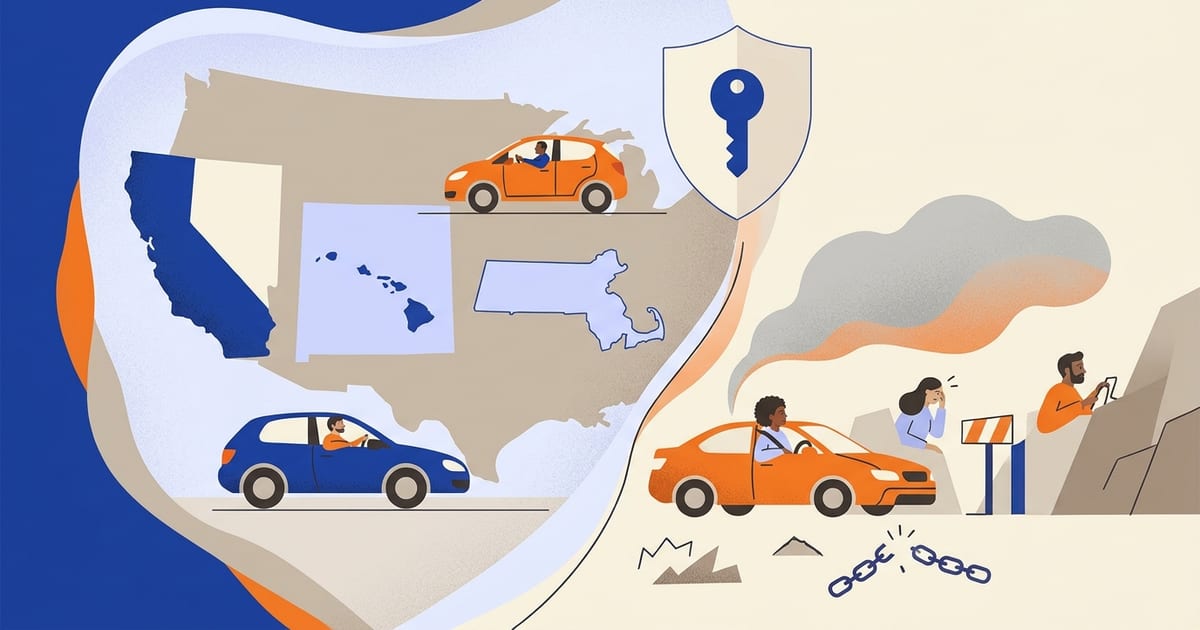
Relocating from a state that uses credit scoring to one that prohibits it—such as California, Michigan, or Massachusetts—fundamentally changes how your auto insurance premium is calculated. Insurers must drop your credit-based insurance score and re-price your policy using statutory factors like driving safety records, mileage, and experience. While this removes credit penalties entirely, state-specific liability minimums and coverage structures will shape your final cost.
How Relocating Eliminates Credit-Based Insurance Scores
If you currently live in a state where auto insurers utilize credit scoring, an adverse financial history can substantially inflate your annual premium. According to data reported by the Insurance Information Institute, credit scoring increases premiums for approximately 23% of drivers in states where it is permitted. When you relocate your primary residence and vehicle garaging address across state lines, your existing policy cannot simply transfer; insurers must issue a new policy conforming strictly to the insurance statutes of your destination state.
In states that ban credit checks in underwriting, the credit surcharge vanishes automatically. The National Association of Insurance Commissioners highlights states such as Massachusetts, where auto insurance rates may not be based on credit, and Michigan, where credit scoring is prohibited under MCL 500.2162. In these jurisdictions, carriers are barred from using credit attributes to assign you to a higher pricing tier or refuse coverage.
| State | Credit Score Permitted? | ZIP Code Rating Permitted? | Key Governing Legal Standard |
|---|---|---|---|
| California | Prohibited | Prohibited | Cal. Ins. Code § 1861.02 (Safety record, miles, years experience) |
| Michigan | Prohibited | Prohibited | MCL 500.2111(4) (Bans credit, postal zone, sex, marital status) |
| Massachusetts | Prohibited | Permitted with limits | NAIC Statutory Summary (Auto rates may not be based on credit) |
| Maryland | New policies only | Permitted | NAIC State Chart (Credit may rate a new auto policy only) |
| Most Other States | Permitted | Permitted | NAIC Credit Guidelines (Cannot be sole basis for decline/cancel) |
Statutory Rating Factors That Replace Your Credit Score
When credit scoring is removed from the pricing algorithm, insurers determine your rates using objective driving indicators established by state law. Under California Insurance Code § 1861.02, rates must be determined primarily by three mandatory factors in decreasing order of importance: the insured's driving safety record, annual miles driven, and years of driving experience. Furthermore, California law requires that drivers who qualify for a Good Driver Discount receive a rate at least 20% below the rate otherwise charged.
Similarly, Michigan law under MCL 500.2111(4) strictly prohibits insurers from setting rates based on credit score, postal zone, home ownership, educational level, occupation, sex, or marital status. As a result, drivers moving to Michigan with past credit blemishes are assessed based on their real driving record and vehicle characteristics rather than demographic and financial criteria.
State-Specific Coverages That Impact Your Final Premium
While removing credit surcharges provides significant financial relief, overall expenditure may be influenced by regional coverage requirements and market loss trends. Countrywide, the National Association of Insurance Commissioners reported an average annual auto expenditure of $1,281 in 2023, but state-level costs vary substantially due to minimum liability limits and local crash frequency.
For example, California Vehicle Code § 16056 establishes mandatory minimum liability limits for policies issued or renewed on or after January 1, 2025, at $30,000 per person for bodily injury, $60,000 per accident for bodily injury, and $15,000 for property damage. In Michigan, the no-fault auto insurance framework includes personal injury protection (PIP) medical options that influence final premiums regardless of credit standing. Additionally, uninsured motorist volume varies by market; Insurance Information Institute data shows uninsured motorist rates reached 22.3% in Michigan and 20.4% in California in 2023, making uninsured motorist coverage an essential consideration.
Checklist: How to Transition Your Insurance When Moving to a Credit-Ban State
- Check the destination state's statutory liability requirements and coverage structures, such as California Vehicle Code § 16056 limits.
- Request proof of prior coverage and your clean driving record from your current carrier to demonstrate continuous coverage and driving experience.
- Compare at least three quotes from carriers operating in your new state to identify those with the lowest baseline rates for your driving profile.
- Notify your insurer of your official relocation date and obtain your new state policy before canceling your prior state coverage.
- Review your new policy declarations page to confirm that no out-of-state credit scoring or unpermitted demographic tiers were carried over.
Questions & answers
Will my car insurance automatically become cheaper if I move to a state that bans credit checks?
If you paid high rates due to poor credit, the credit penalty will disappear. However, whether your total bill drops depends on the destination state's overall costs, mandatory coverage requirements, and minimum liability limits.
Can an insurer check my credit if I move to California or Michigan?
Under California Insurance Code § 1861.02 and Michigan MCL 500.2111(4), insurers are prohibited from using credit scores to set auto insurance rates or determine eligibility for standard coverage tiers.
What happens if I move to Maryland?
Maryland law permits insurers to use credit history only to rate a new auto policy; carriers cannot re-rate or increase premiums at renewal based on changes in credit history.
Do I need to cancel my existing policy before moving?
Never cancel your existing policy before establishing new coverage in your destination state. A lapse in coverage creates a non-standard driving status, which can significantly raise premiums across all states.
Terms: Credit-based insurance score, Rating factor, Rating tier, Re-rate, Premium
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- MCL 500.2111 — permitted and prohibited rating factors — Michigan Legislature, MCL 500.2111(4)Primary lawInsurers may not set auto rates on sex, marital status, home ownership, educational level, occupation, postal zone or credit score (as defined in § 2162).
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Vehicle Code § 16056 — minimum liability limits — California Legislative Information, Cal. Veh. Code § 16056Primary lawPolicies issued or renewed on/after 1 Jan 2025: $30,000 per person / $60,000 per accident bodily injury / $15,000 property damage. From 1 Jan 2035 the limits rise by $20,000 / $40,000 / $10,000 (to 50/100/25).
- State chart: use of credit reports/scoring in underwriting — National Association of Insurance Commissioners (2025)State insurance regulatorState-by-state statutory summary; e.g. Massachusetts (auto rates may not be based on credit), Michigan (credit score prohibited, MCL 500.2162), Maryland (credit may rate a new auto policy only).
- Credit-based insurance scores (insurance topic) — National Association of Insurance CommissionersState insurance regulatorIn most states insurers may not use a credit score as the sole reason to raise rates or decline, cancel or non-renew; many states require adverse-action notices.
- Background on: Insurance scoring — Insurance Information InstituteIndependent researchWhat credit-based insurance scores are; Arkansas regulator data showing credit lowered premium on ~57% of auto policies and raised it on ~23%.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Estimated percentage of uninsured motorists by state, 2017–2023 — Insurance Information Institute (2025)Statistical dataIRC time series by state; 2023: Mississippi 28.2%, New Mexico 24.1%, D.C. 23.1%, Michigan 22.3%, Florida 20.6%, California 20.4%, Texas 14.5%; lowest Maine 5.7%.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Entry
Michigan Auto Insurance Without Credit Checks: State Rules Explained
Understand Michigan's statutory ban on credit scoring under MCL 500.2111, how auto insurance rates are calculated, and how drivers can save on coverage.
Parent guide
States That Ban Credit in Auto Insurance
The states where insurers cannot use credit to rate auto insurance—California, Hawaii, Massachusetts—plus Michigan's credit-score ban and the states that restrict it.