By Alicia Moreno · Research Writer
Published · Updated
Answer in brief
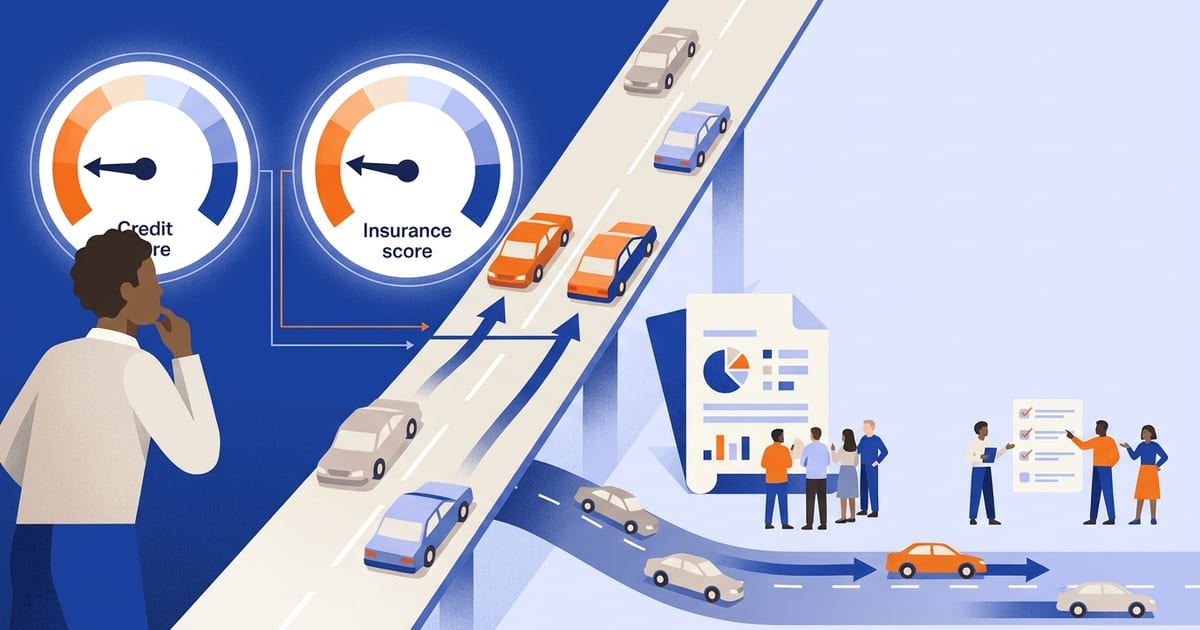
An adverse action notice is the letter insurers must send when information in your credit report leads to a higher rate, a lower tier or a declined application. It names the credit bureau used, lists the main reasons, and tells you how to get a free copy of the report within 60 days. Use it to find and dispute errors and to understand which factors to work on.
What the notice contains
- The action taken (higher rate, tier placement, denial).
- The credit bureau whose report was used, with contact details.
- Up to four or five key reasons the score was not higher.
- Your right to a free report copy within 60 days and to dispute inaccuracies.
What to do
- Request the free report from the named bureau.
- Check every account for errors—wrong balances, accounts that are not yours, paid items showing as unpaid.
- Dispute errors with the bureau; they must investigate within 30 days.
- If the report changes, ask your insurer to re-rate.
- Work on the listed reasons; see improving your score.
Terms: Adverse action notice, Credit-based insurance score
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Background on: Insurance scoring — Insurance Information InstituteIndependent researchWhat credit-based insurance scores are; Arkansas regulator data showing credit lowered premium on ~57% of auto policies and raised it on ~23%.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- Insurance research and advocacy — Consumer Federation of AmericaConsumer guidanceConsumer-side research on auto insurance pricing, non-driving rating factors and affordability.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Entry
Can an Auto Insurer Cancel Your Policy if Your Credit Score Drops?
Learn whether an auto insurer can cancel or non-renew your policy over a drop in credit, what state laws require, and your rights under adverse action rules.
Parent guide
How Credit Affects Auto Insurance Rates
What a credit-based insurance score is, how it differs from a credit score, how much it moves premiums, and why insurers are allowed to use it.